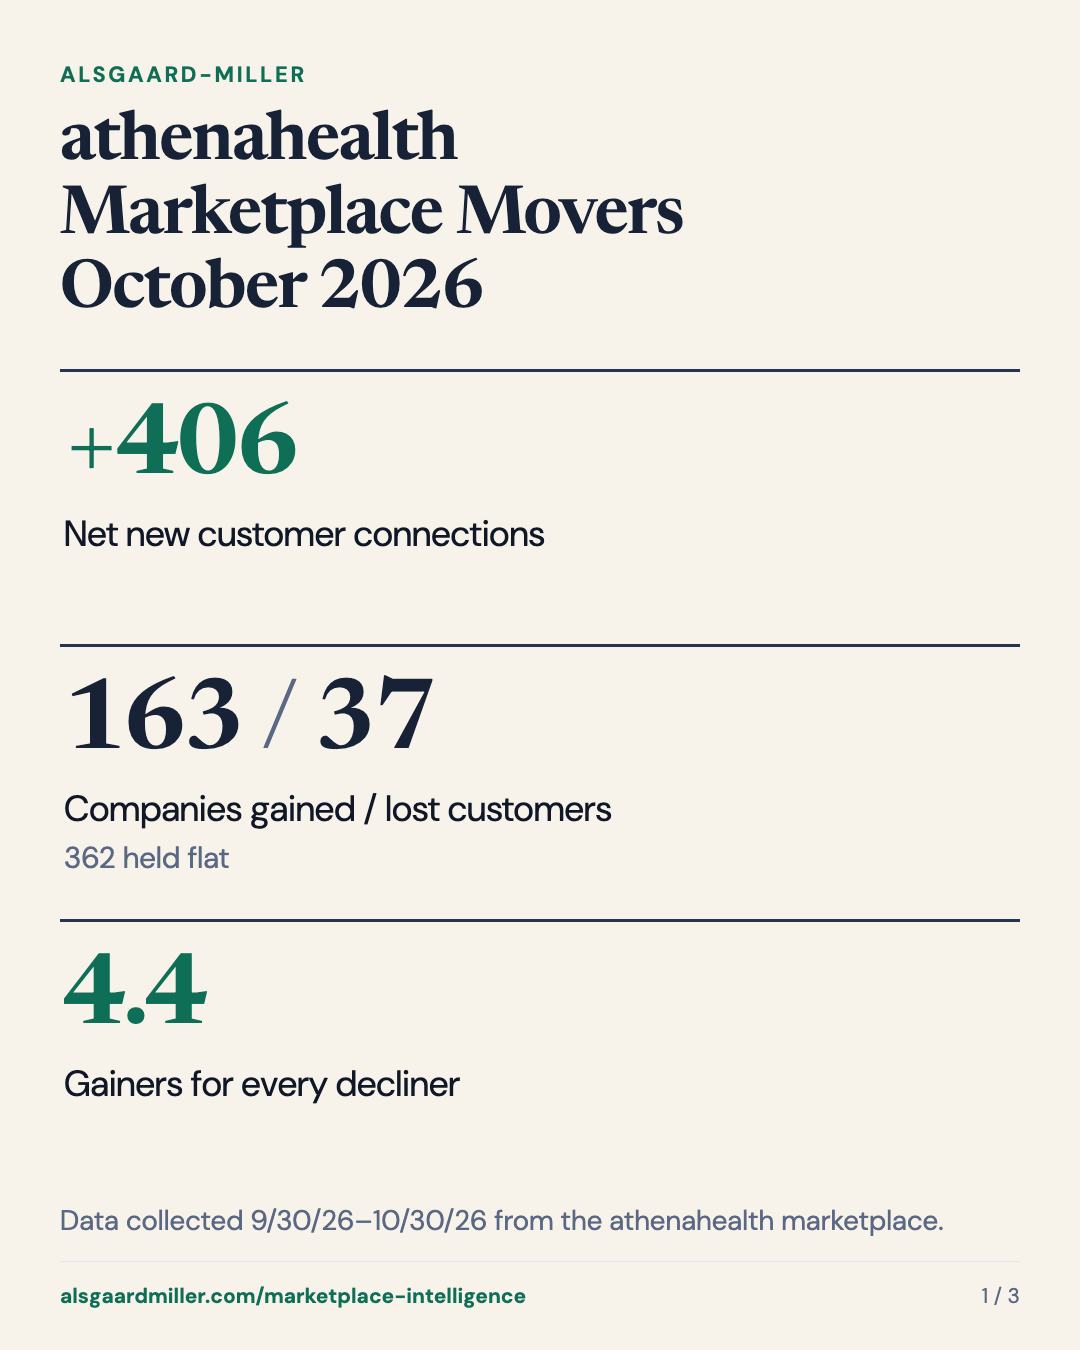
In October on the athenahealth marketplace, 163 companies added customers, 37 lost them, and 362 held flat. That works out to roughly 4.4 gainers for every decliner, and a net gain of 406 customer connections across the marketplace. That's the highest gainer-to-decliner ratio since July, and a return to positive net growth after September's outlier drop of 346 connections from a single company.
Most customers added
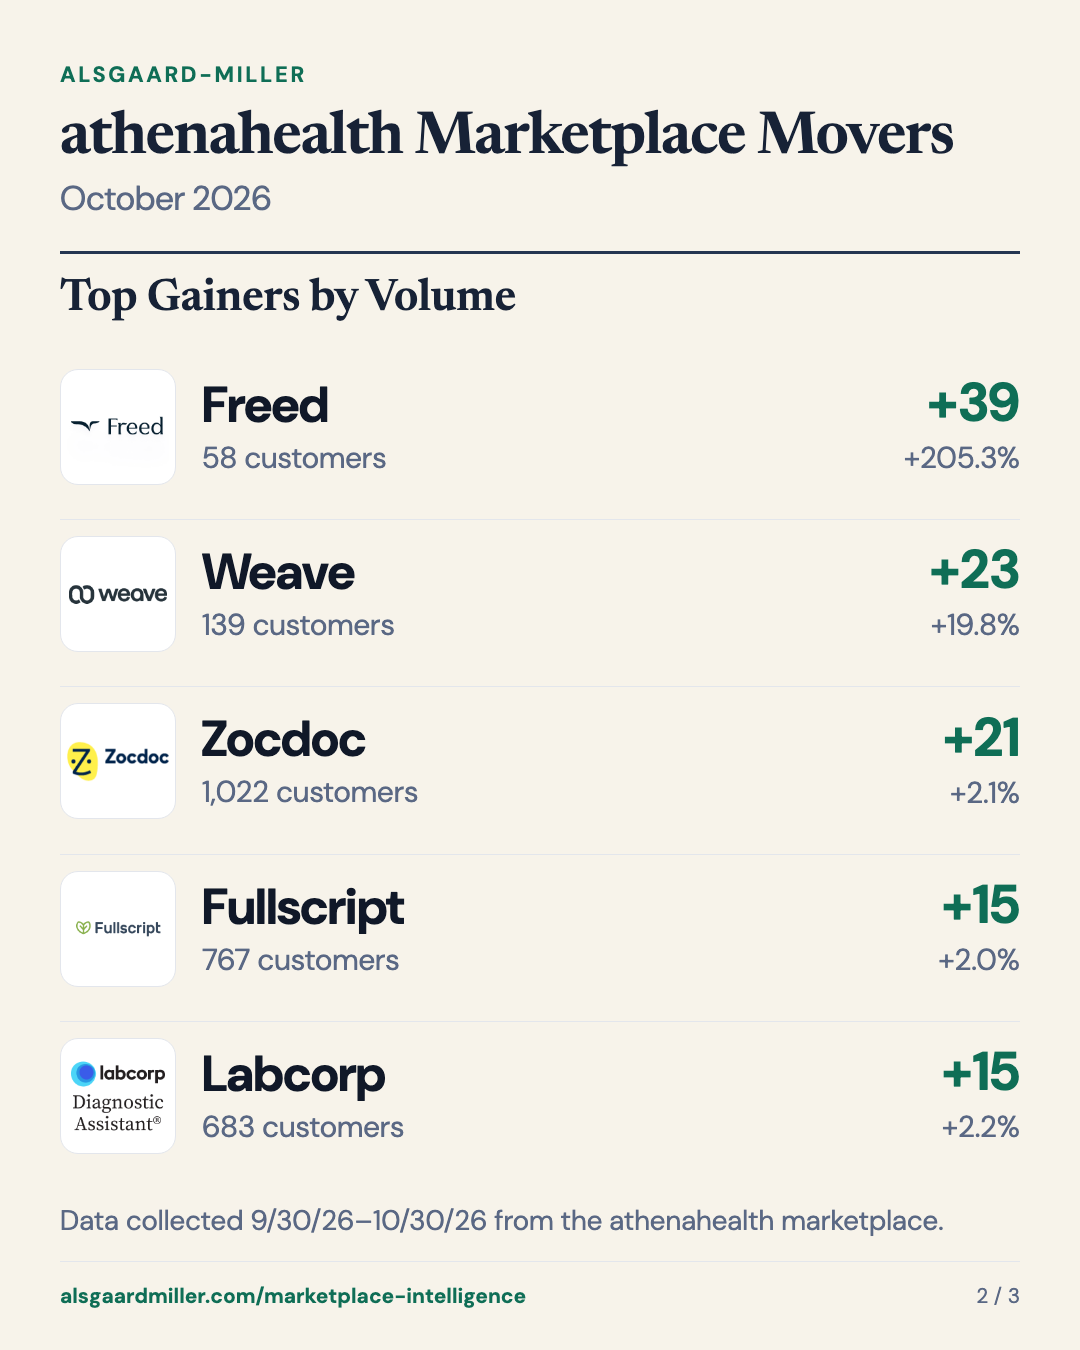
Freed wins the month by a wide margin, adding 39 customers to reach 58. They went from 7 to 14 in August, 14 to 19 in September, and 19 to 58 in October. That's 8x in three months for an AI scribe that sells direct to clinicians, plus AI Phone Agents. In May they raised a $30M Series A led by Sequoia (Freed press release).
Weave added 23 customers to reach 139. Fifth month in a row on this list, up from 7 customers in May. The bigger news is that Weave is no longer a public company. Francisco Partners closed its all-cash acquisition on October 26 at $7.40 a share, about $650 million (Globe and Mail). Their formal entry into the Marketplace program was only announced in June, so this entire run has happened in the five months since.
Zocdoc added 21 customers and now sits at 1,022. They crossed 1,000 in September without making the list. Two pieces of news in October. They acquired Sohar Health, an insurance eligibility verification company, the first acquisition in Zocdoc's nearly 20-year history (MobiHealthNews). Then on October 28 they opened the platform to AI agents. Zocdoc says agent traffic on its platform has grown nearly 30x since July, and now they have and MCP server and APIs for agents to search providers and book appointments on behalf of patients (Healthcare Dive). The first partner is Instinct (which also found me two tickets to Dune for the opening week), connecting to Zocdoc's MCP server (MobiHealthNews).
Fullscript added 15 customers and is now at 767. They've been on this list six of the last seven months. Nothing new since the L Catterton and Altas investment I covered in September.
Labcorp added 15 customers to Diagnostic Assistant, now at 683. Fourth time on this list since June. In August they added their AI-powered Test Finder inside Diagnostic Assistant, so providers can look up tests and specimen requirements through conversational prompts without leaving the chart (Labcorp). Q3 earnings on October 28 showed diagnostic revenue up 6.5% (Benzinga transcript). Same story as the last three times: free to practices that already send to Labcorp, and still growing.
Fastest growth
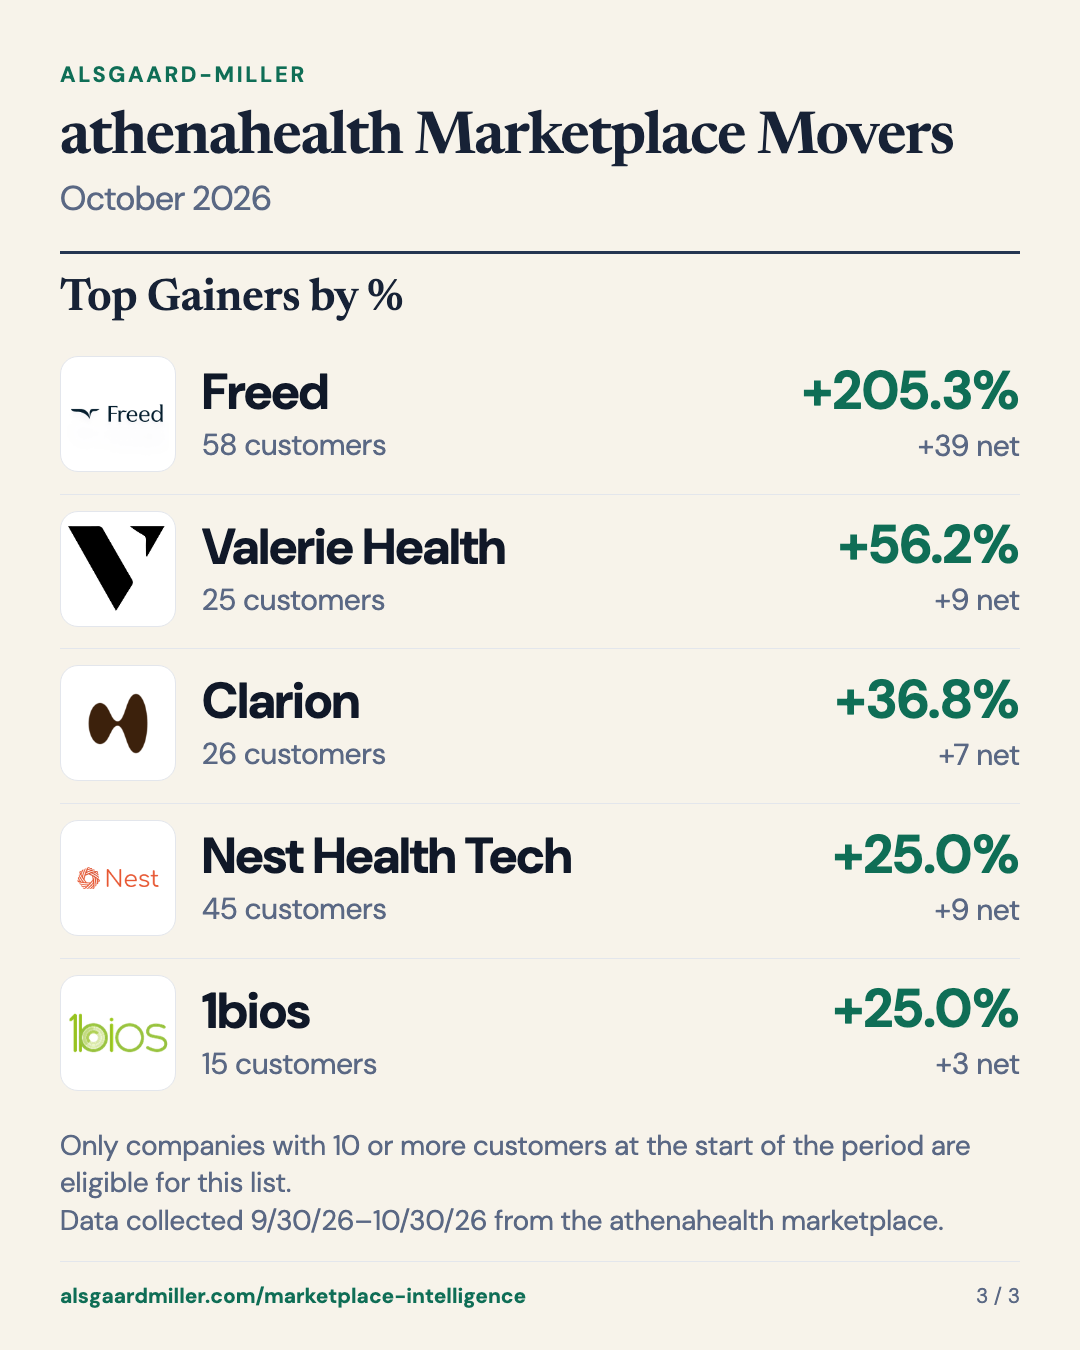
Freed grew 205.3%. See above.
Valerie Health grew 56.2%, from 16 to 25 customers. Second time on this list after July, when they went from 12 to 15. They handle referrals, faxes and scheduling with AI agents plus humans in the loop. They raised a $30M Series A led by Redpoint in December, bringing total funding to $39 million (press release).
Clarion grew 36.8%, from 19 to 26 customers. This is their first time in the rankings. Back in July they were one of four listings that went from zero to a handful of customers overnight, so I excluded them. They're an AI front office for phones, texting and web chat. In September they announced a $10M seed led by Accel with participation from Y Combinator (StartupDB). Their pricing is outcome-based: they only charge when the AI resolves a patient request (Clarion). I haven't seen that model on the marketplace before.
Nest Health Tech grew 25.0%, from 36 to 45 customers. New to me. They do business as Nest Genomics, a YC company that joined the marketplace in October 2024 with a genetics copilot covering cancer risk assessment, test ordering and long-term management inside the EHR (press release).
1bios grew 25.0%, from 12 to 15 customers. Also new to the list. They run RPM and CCM programs for independent practices, with an in-house care team handling enrollment, engagement, service delivery and billing (1bios). Small base, but RPM and CCM companion apps have been quietly consistent all year.
The front office, again
Weave, Valerie Health and Clarion all sell AI for the front office. That's three of this month's ten. Last month it was three different companies in the same category.
Methodology
Customer counts pulled from the athena marketplace between September 30 and October 30. Minimum starting base of 10 customers to qualify for the rankings. Mirrored listings from the same company are collapsed into one entry, in both the rankings and the summary numbers.
Want a deeper read on a specific category or partner? That's what I do for clients.